
Loading…
Loading…

Replacing a six-figure salary with dividends at 61 sounds straightforward until you realize the yield you choose can swing your required portfolio by more than three million dollars in either direction.
STAG Industrial gets its prior buy rating from June reaffirmed, ahead of the upcoming Q3 results due in late October. Positives include a portfolio growth trajectory, a national footprint in many regions, investment-grade rating, and low tenant concentration risk. Positive FFO trends and outlook should continue supporting the dividend, which has a lower risk of being cut.
A fixed annuity promises a guaranteed paycheck but quietly loses ground to inflation every year, while a dividend portfolio starts lower yet can grow into something far larger. Before committing $615,000 either way, one comparison changes how both options look.
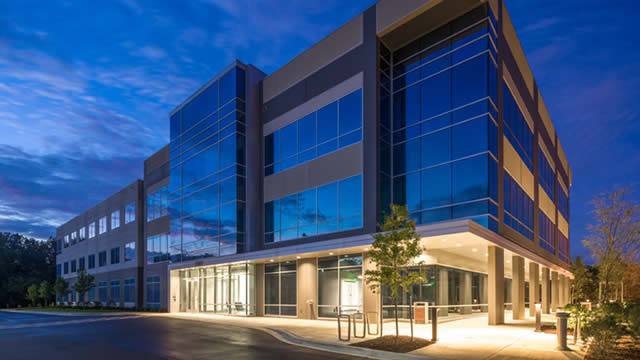
STAG Industrial has sold off 15% since July, now trading at a 20% NAV discount and 12.9x forward FFO, presenting an opportunistic entry. Recent FFO/share flattening was a temporary timing issue from lease roll gaps and development completions; underlying fundamentals remain strong with 97.6% of 2026 expiring leases handled and +20.5% rent spreads. STAG's smaller median warehouse size (110K sq ft) insulates it from oversupply risk and supports property-level outperformance versus peers focused on larger footprints.
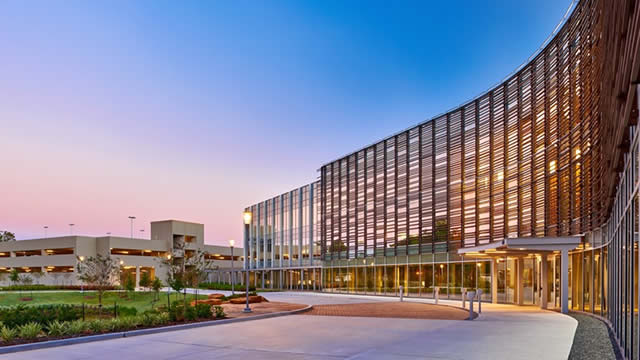
Warehouses handling every online order and factory shipment are back in high demand, and five industrial REITs are converting that traffic into growing dividend checks.
Stag Industrial (NYSE: STAG - Get Free Report) and LXP Industrial Trust (NYSE: LXP - Get Free Report) are both mid-cap real estate companies, but which is the better business? We will contrast the two businesses based on the strength of their valuation, dividends, profitability, earnings, analyst recommendations, risk and institutional ownership. Insider and Institutional Ownership 88.7%
A portfolio that never sells a share sounds like a fantasy, but the math behind three income buckets reveals a specific yield where the whole strategy starts to fall apart.
Every year, a five-figure slice of income from high-yield REITs and BDCs quietly routes to the IRS instead of your pocket, and the bracket you sit in determines exactly how much damage a taxable account does over time.