
Loading…
Loading…

DLR's Q3 results may benefit from strong leasing, a record backlog and rising AI and cloud demand, with rental revenues and total revenues expected to grow.
Baron Real Estate Income Fund decreased 7.58% (Institutional Shares) in the third quarter, underperforming the MSCI US REIT Index, which decreased 6.33%. Welltower is a leading owner and operator of senior housing communities across the U.S., Canada, and the U.K., and is the largest health care REIT by market capitalization. We initiated a position in AAON, Inc., following a disappointing second quarter earnings result.
U.S. markets remained unsettled as cracks emerged in the AI investment boom, while another oil-price surge complicated the inflation outlook ahead of Wednesday's Fed decision. Treasury yields fell for a third straight week as AI-related risk-off flows strengthened, with markets now assigning just 10% odds of an October hike despite still-elevated energy prices. REITs rallied for a third-straight week as earnings opened on an encouraging note: 15 REITs raised full-year FFO guidance, reinforcing the view that fundamentals remain healthier than recent price action.
AI data centers consume enough power to light entire cities, and the landlords collecting rent on those facilities are quietly growing their dividends.
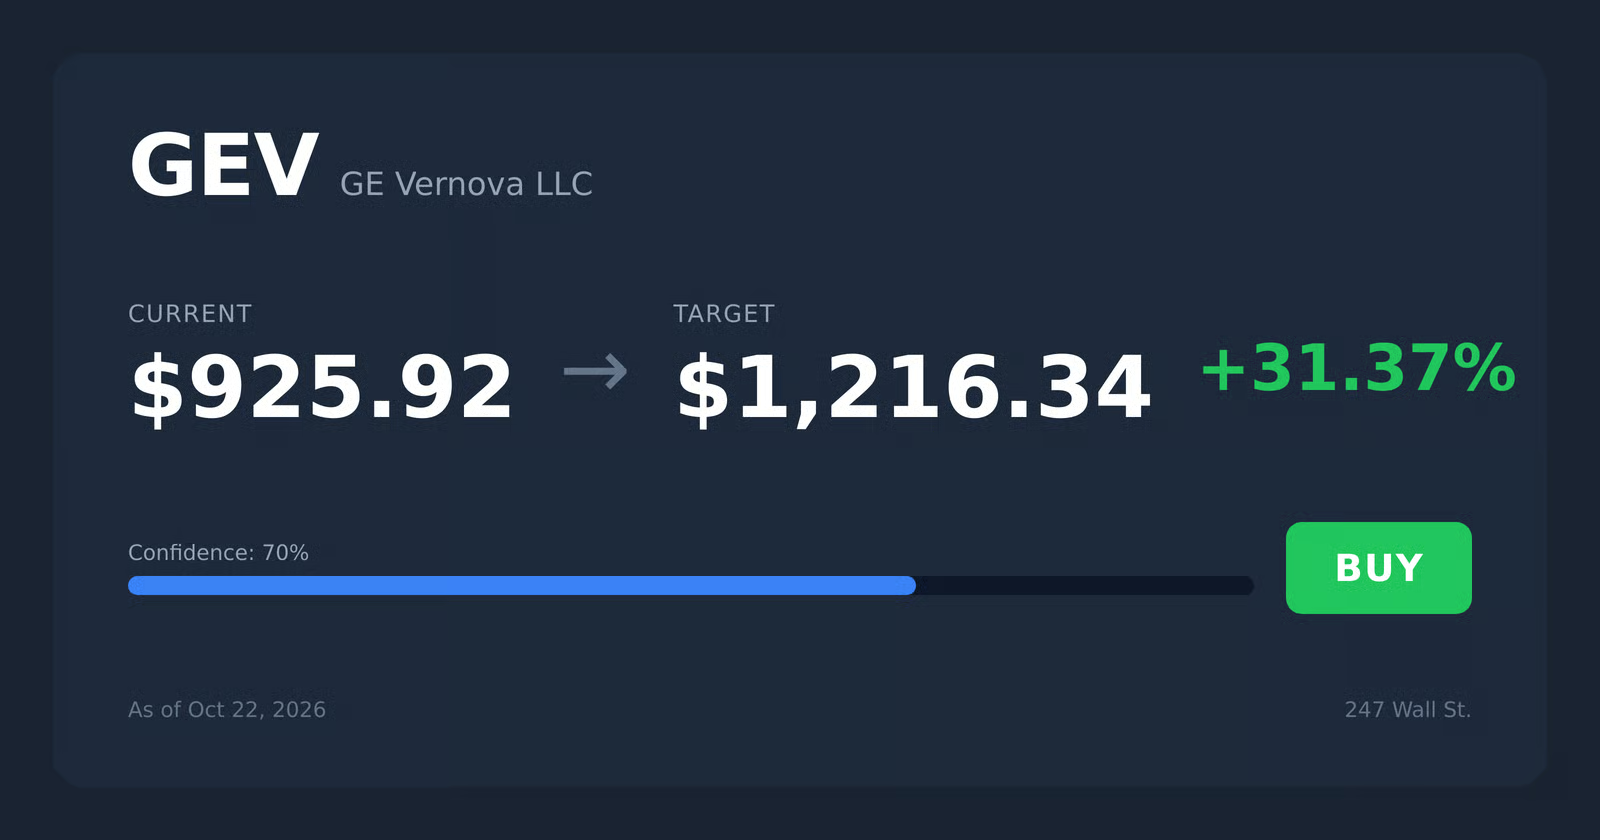
Trump declared on Truth Social that data center developers must generate their own power and pay neighbors a dividend, but his posts named no amounts, no enforcement mechanism, and no federal program to back any of it up.
Wall Street analysts delivered a flurry of bold calls Wednesday, including a double-downgrade that shocked one cybersecurity giant and a sharp cut on a beloved restaurant chain. Find out which stocks got upgraded, buried, or newly covered before the market opens.
Rate Shock: REITs enter earnings season on their back foot amid a renewed surge in long-term rates, facing a materially different cost-of-capital and financing environment than just three months ago. The rate surge is again stressing highly leveraged borrowers, particularly across private markets. Public REITs are better positioned, but remain exposed through refinancing, tenant credit, and equity valuations. Higher rates have brought an important silver lining: years of expensive capital are finally curbing construction, with shrinking pipelines beginning to support occupancy, rents, and landlord pricing power.
Digital Realty Trust offers contracted growth potential at $174.20, with success hinging on lease commencements and effective capital allocation. DLR's transparent growth is underpinned by signed leases, a robust backlog, and rising renewal rents, supporting a 2027 core FFO estimate of $9.10 per share. Valuation is reasonable at ~21.3x forward core FFO, with upside to $209 if execution aligns with expectations and new developments are delivered on schedule.