
Loading…
Loading…

Amazon.com, Inc. has underperformed other AI hyperscalers, which creates a buying opportunity for a catch-up rally, as I expect robust 3Q earnings. While Q3 retail revenue guidance seems soft, driven by the timing of Prime Day and an unfavorable currency impact, consumer spending remains strong enough to limit downside risk. I expect a Rule of 80 for AWS by year-end and 90 before FY2028, driven by a mounting backlog and accelerating capex growth that narrows the supply shortage gap.
A look at Harvard Management Company's latest public filings reveals a massive concentration in tech and AI leaders such as SpaceX, TSMC, Cerebras, Amazon, and Alphabet.
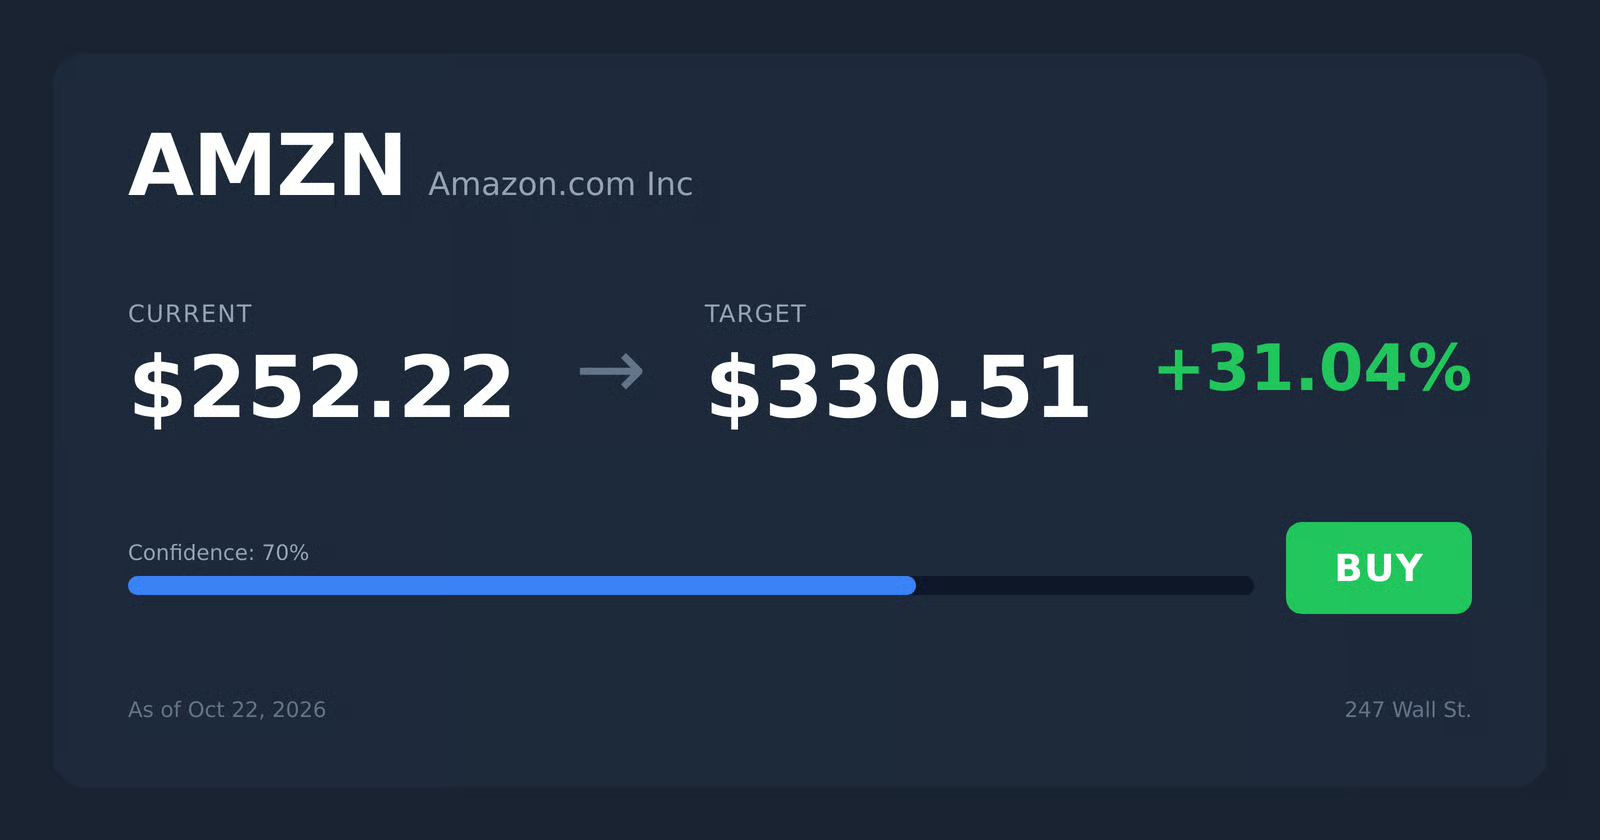
E-commerce and cloud giant Amazon (AMZN) released new software to simplify adoption of its Trainium AI chips, while shares traded at $252.31, down 3.83%, at 11:
Elon Musk has raised the idea of competing with the world's largest online retailer. A user said that Amazon (NASDAQ:AMZN | AMZN Price Prediction) was blocking Grok bots from placing orders.
Artificial intelligence has become Wall Street's biggest investment opportunity and potentially its biggest vulnerability. Technology companies are committing hundreds of billions of dollars to data centers, chips, and computing infrastructure, betting that AI will transform the economy.
Amazon.com, Inc.'s Q3 earnings will confront heightening investor scrutiny over its intensifying AI capex cycle, as negative FCF and tightening financial conditions raise concerns about investment returns. While sustained AWS acceleration and margin expansion demonstrate profitable demand conversion, continued AMZN operating leverage will be critical to strengthening ROI visibility amid its elevated AI spending trajectory. Emerging cyclical headwinds from resurgent inflation and rate hikes, compounded by soaring oil prices, also threaten Amazon's core commerce growth and cost structure ahead of the crucial holiday shopping season.
Amazon (AMZN) doesn't possess the right combination of the two key ingredients for a likely earnings beat in its upcoming report. Get prepared with the key expectations.
Amazon's cloud business is accelerating at its fastest pace in 18 quarters, but the company just burned through billions in free cash flow. Whether that spending fuels massive gains or derails a monthly investment plan depends on a few key numbers to watch.